Common Retail Planning Errors: What Developers Should Avoid
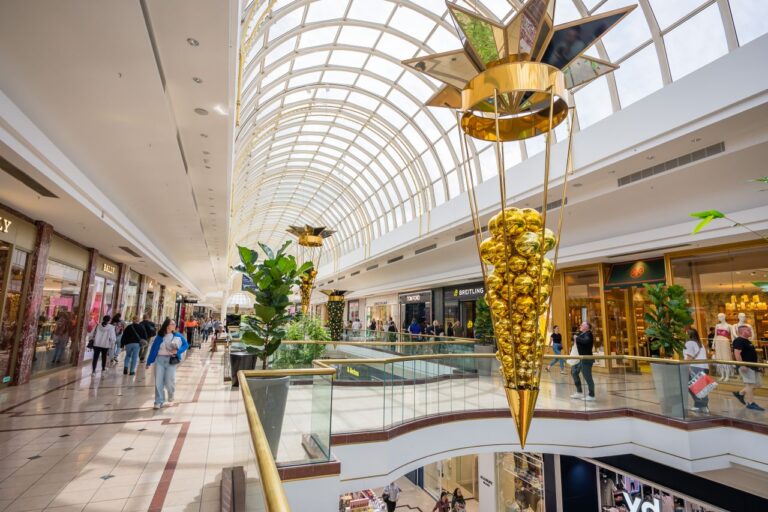
Retail developments that underperform are rarely done by a single bad decision. More often, they are weakened by a sequence of smaller ones made early and seldom revisited. Land is bought before the catchment is tested, a concept is drawn before any retailer is consulted, and construction starts before the design is resolved.
Each decision looks reasonable at the time. Together, they set a ceiling on what the asset can ever earn.
Across 200 projects in over 30 countries, we have seen the same errors recur in the GCC, MENA and beyond. The ten below are the ones that cost developers most, and nearly all of them can be avoided with discipline at the planning stage.
Key Takeaway:
- The most expensive retail planning errors are made before construction begins, when they are still cheap to correct.
- Feasibility, positioning, tenant mix and design should be settled in that order, with each stage informing the next.
- Land price, construction cost and rental rates mean little until they are tested against what the catchment can support.
- Flexible units, clear circulation and well-planned access protect the value of an asset long after opening day.
1. Bypassing Rigorous Feasibility Studies
Conviction is valuable in development. It is a poor substitute for data.
The most common form of this error is a business case built on instinct. Rents are assumed from the strongest comparable rather than the typical one. The catchment is judged by its traffic rather than its spending power. The financial model assumes the centre opens fully let.
A proper feasibility study tests each of these assumptions. It maps the primary, secondary and tertiary trade areas by drive time, measures existing and pipeline supply, and estimates the footfall required to support the proposed leasable area. The financial model is then stress-tested against slower absorption, rent-free periods and the initial vacancy most new retail centres carry in their first years. If a project only works when everything goes to plan, it will not perform sustainably.
2. Misaligned Market Positioning
A centre that offers what every nearby centre already offers is left to compete on rent, and retail landlords rarely win that contest. Positioning answers a simple question: why would a shopper choose this destination over the one they already use?
The second form of this error is a mismatch of tier. A luxury concept placed in a value-conscious catchment will struggle to sign the brands it was designed for. It then fills with tenants it was never designed to suit.
Positioning should follow the demographic and spending evidence rather than the developer’s ambitions for the brand. Once agreed, it should guide every later decision, from unit sizes and finishes to the tone of the marketing presented to prospective retailers.
3. Skipping Comprehensive Site Due Diligence
Inexpensive land is often inexpensive for a reason. Before acquisition, developers should commission geotechnical testing, confirm that power, water and drainage capacity can serve a scheme of the intended size, and review zoning and planning controls in full. Restrictions on use, height, setbacks or signage can quietly remove much of the value a site appeared to offer.
Commercial due diligence matters just as much. Access from the surrounding road network, visibility from main routes, traffic patterns at peak hours and the strength of competing retail all shape trading performance. A site that saves money on acquisition but costs it back in remediation, utility upgrades or weak trade is rarely the bargain it seemed.
4. Failing to Curate a Cohesive Tenant Mix
Under the pressure of a leasing campaign, any tenant willing to sign can look like progress. Yet a shopping centre works as a portfolio, and every lease affects the performance of the units around it. A mix assembled one deal at a time tends to produce clusters of similar offers, weak adjacencies and too little reason for shoppers to stay.
A planned merchandise mix starts with anchors positioned to draw footfall across the whole flooA r plate. Complementary brands are then grouped so that one visit leads naturally to the next, while food and beverage operators are placed to extend dwell time and support evening trade.
The mix should be agreed before leasing begins, with target retailers identified for each unit. That way, rent is an important criterion for every deal but never the only one.
5. Overlooking Parking and Site Access
For most centres in the region, the shopping experience begins at the road junction. Confusing entry and exit points, queues at the main entrance, poorly signed routes and too few spaces at peak times push shoppers towards an easier alternative before they reach the front door.
Parking should be designed alongside the building from the outset. That means testing peak demand against the planned mix, since cinemas, supermarkets and restaurants each create different peaks. It also means separating service traffic from customer traffic and linking each parking level clearly to the main entrances and vertical circulation. In a hot climate, shaded and covered parking is a practical requirement rather than a design flourish.
6. Underestimating Budgets and Timelines
Development budgets tend to concentrate on hard costs such as structure, envelope and building services. Soft costs receive far less scrutiny, although design and engineering fees, authority charges, permits, leasing costs, tenant incentives and finance charges can add materially to the total. A contingency that looks generous at concept stage is often spent well before handover.
Timelines deserve the same realism. Authority approvals, utility connections and design revisions take time that seldom appears in an optimistic programme, and every delay carries its own cost in finance charges and deferred income. A critical path plan that ties construction milestones to leasing milestones gives the developer an honest view of when the centre can open and when it will begin to earn.
7. Rushing the Preconstruction Phase
The pressure to break ground early is understandable. Every month of delay has a cost, and visible progress reassures investors and lenders. Starting construction before the architectural, structural and services designs are fully coordinated, however, simply moves the problem to site, where it becomes far more expensive to solve.
Uncoordinated drawings lead to clashes between structure and services, redesign during construction and change orders that erode both budget and programme. Retail schemes are particularly exposed because tenant requirements for ceiling heights, loading, drainage and shopfront dimensions must be reflected in the base build. Resolving these questions on paper costs a fraction of resolving them once the frame is up.
8. Neglecting the Customer Journey
Shoppers judge a centre by how easy it is to use. Layouts without clear sightlines, awkward changes of level and long corridors that end without a destination create areas most visitors never reach. These dead zones depress footfall, and the smaller inline tenants located there are the first to feel it.
Good circulation is designed deliberately. Anchors and key attractions belong at the ends of primary routes so that shoppers pass the units in between. Escalators and lifts should draw people further into the centre rather than towards the exits. Clear wayfinding, consistent sightlines and well-placed seating and amenities reduce disorientation and encourage longer visits. These decisions belong at the schematic design stage, when they cost least to change.
9. Designing Rigid, Inflexible Spaces
Retail changes faster than buildings do. A unit built around one tenant’s exact specification can be hard to relet when that tenant leaves, and space that cannot be combined or subdivided limits a landlord’s options as the market moves.
Flexibility starts with the structural grid. Regular column spacing, demising walls that can be relocated and services capacity that allows for a change of use all give the asset room to adapt. Retailer needs are shifting as online and physical channels converge. Some now want space for click and collect, returns or small-scale fulfilment, while others need more room for food, leisure and experiences. A centre that can absorb these shifts without major structural work holds its value for longer.
10. Choosing Contractors Solely on Price
The lowest tender is attractive on paper and can prove costly in practice. Shopping centres involve phased handovers to tenants, complex building services, fit out interfaces and opening dates that leasing commitments depend on. A contractor without relevant experience may underestimate that complexity at tender stage, then recover the difference later through delays, claims and variations.
Contractor selection should weigh retail experience, the strength of the proposed site team, financial standing and the realism of the programme alongside price. Speaking with developers the contractor has recently worked for is one of the most reliable checks available. A late opening affects far more than the construction budget. It strains commitments to tenants, unsettles anchor relationships and weakens the launch the entire leasing campaign was built around.
Why the Order of Decisions Matters
Most of these errors share a root cause: decisions taken out of sequence. Land is bought before demand is proven, design is fixed before leasing input is sought, and construction begins before the drawings are coordinated.
The developments that perform best follow a clear order. The market assessment defines the positioning, the positioning shapes the merchandise mix, and the mix informs the design brief. Each stage is tested against the one before it, so problems surface while they are still inexpensive to solve.
How PHIL McARTHUR & PARTNERS Supports Developers
PHIL McARTHUR & PARTNERS was founded in Dubai in 2012 by Phil McArthur and advises shopping centre developers, investors and asset owners across the GCC, MENA and international markets. Our team brings more than 150 years of combined experience and has contributed to over 200 projects in more than 30 countries, representing over USD 20 billion in project investment.
Our work spans market research and feasibility studies, concept design review, retail leasing and marketing strategy, financial modelling and the review of operating centres. On projects such as Jeddah Central Development, DIFC in Dubai and Lusail Boulevard in Qatar, our role has ranged from market assessment and competitive positioning to concept design validation and leasing strategy. In each case, the aim is the same: to ground the decisions that shape a retail asset in evidence before they become expensive to reverse.
If you are planning a new retail development or reviewing one already under way, speak with our team before the key decisions are fixed. Contact us to discuss your project.
Frequently Asked Questions
What are the most common retail planning errors developers make?
The most common errors are weak feasibility work, unclear market positioning, incomplete site due diligence, an unplanned tenant mix, poor parking and access, unrealistic budgets and timelines, a rushed preconstruction phase, neglected circulation, inflexible unit design and choosing contractors on price alone. Most stem from making decisions before the evidence is in place.
Why is a feasibility study essential before a retail development?
A feasibility study tests whether the catchment can support the proposed scheme. It examines population, spending power, competing supply, achievable rents and likely absorption, then stress tests the financial model against slower leasing and early vacancy. Without it, the project rests on assumptions that are hard to correct once the land is bought.
How does tenant mix affect the performance of a shopping centre?
Tenant mix determines why people visit, how long they stay and how much they spend. Well placed anchors draw footfall through the centre, complementary brands encourage shoppers to move between stores, and food and beverage extends dwell time. A mix built only on who will pay rent tends to create dead zones and weaker sales.
What should developers check during retail site due diligence?
Developers should verify ground conditions, utility capacity, zoning and planning controls, road access, traffic patterns, visibility from main routes and the strength of nearby competing retail. Technical issues raise costs, while commercial issues limit trading potential. Both should be understood fully before the land is acquired.
When should a retail advisor be involved in a development?
Ideally, before the land is acquired or the concept is fixed. Early involvement allows the market assessment to shape positioning, unit mix and the design brief. Retail input is typically most valuable up to the schematic design stage, when changes to layout, circulation and tenant planning still cost little to make.